
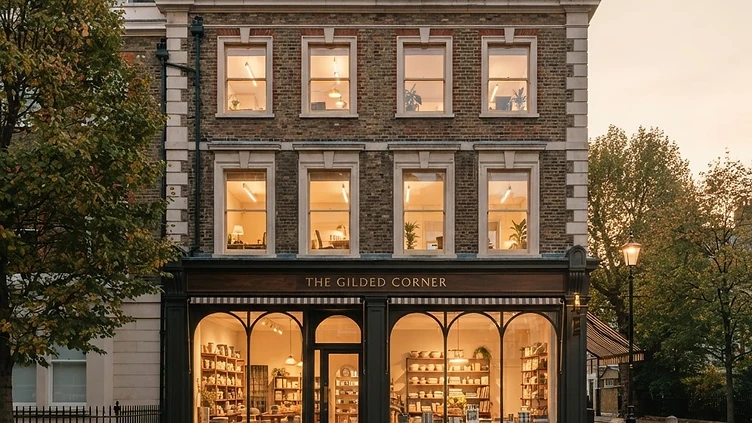
Discover why semi-commercial properties offer UK investors a unique blend of risk mitigation, higher yields, and better tax efficiency for a robust portfolio.
Understanding Semi-Commercial Property Assets
In the landscape of UK property investment, the lines between 'residential' and 'commercial' are often drawn sharply. However, there exists a vital middle ground that many experienced investors overlook: the semi-commercial property. Often referred to as mixed-use assets, these buildings consist of a commercial space on the ground floor—such as a retail unit, office, or workshop—with self-contained residential accommodation above. For the investor looking to diversify their portfolio and mitigate risk, these assets offer a unique proposition that bridges the gap between high-yield commercial income and the consistent demand of the residential market.
The Dual Income Advantage
The primary appeal of semi-commercial property is risk diversification. A standard residential Buy-to-Let (BTL) relies entirely on the residential rental market. A pure commercial investment, conversely, is tethered to the economic health of the business sector. Semi-commercial assets allow you to straddle both. If the retail unit experiences a void period, the residential income provides a reliable baseline to cover service costs and mortgage interest. Conversely, if the residential sector faces cooling demand, the longer-term commercial leases can provide a stable foundation of income. This structural resilience is why many savvy investors are shifting their focus toward exclusive opportunities for high-yield, off-market commercial acquisitions to build more robust portfolios.
Navigating Finance and Valuation
Financing semi-commercial property is distinct from standard residential lending. Lenders evaluate these assets using a 'split-basis' approach. The residential portion is typically valued similarly to traditional housing, while the commercial aspect is assessed based on the yield—the annual rental income expressed as a percentage of the property's value. Because these properties are specialist, high-street lenders are often less inclined to lend, pushing investors toward specialist finance providers. These lenders understand the complexities of mixed-use valuations, such as business rates and the longer-term security of commercial lease agreements. Understanding the Commercial Mortgage Backed Securities (CMBS) landscape and how commercial lenders calculate 'Debt Service Coverage Ratio' (DSCR) is essential before committing capital.
Tax Efficiency and Lease Structures
From a tax perspective, semi-commercial property is often more efficient than pure residential investments. Because a portion of the building is commercial, you may be able to structure the acquisition through a Limited Company more effectively, potentially allowing for the deduction of mortgage interest as a business expense. Furthermore, commercial tenants typically pay their own utility bills, insurance, and business rates, and in many cases, are responsible for maintenance under a 'Full Repairing and Insuring' (FRI) lease. This dramatically reduces the administrative burden on the landlord compared to a standard Assured Shorthold Tenancy (AST) in the residential sector.
Mitigating Risks in Mixed-Use Assets
While the upside is clear, semi-commercial assets carry specific risks. Commercial voids can be longer than residential ones; finding the right business tenant takes patience and professional due diligence. Investors must ensure that the commercial unit is viable for a variety of uses, or 'Use Classes', as governed by the Town and Country Planning (Use Classes) Order. Flexibility is your friend here; a space that can easily convert from a retail shop to an office or a boutique cafe is far more liquid than a highly specialised industrial unit. Always conduct thorough site surveys to ensure that the residential and commercial elements have separate metering and independent access, which prevents management headaches.
The Strategic Appeal
Semi-commercial properties are rarely found in the public domain. They are often held within family portfolios or private estates for decades and are typically traded through professional networks before ever reaching an open market listing. As the UK high street undergoes a period of repurposing, these assets are gaining value, particularly those in secondary or tertiary locations where local councils are encouraging residential development. By focusing on the fundamentals—location, tenant covenant strength, and asset flexibility—investors can secure cash-flow positive assets that outperform traditional buy-to-let properties in the long run.
Key takeaways
- Diversify risk by layering residential income with commercial returns, protecting your portfolio against sector-specific downturns.
- Leverage specialist finance to accommodate mixed-use valuations, which differ significantly from standard residential mortgage criteria.
- Seek properties with flexible Use Classes to ensure the commercial space remains attractive to future tenants.
- Focus on properties with independent access and separate utility metering to simplify property management and reduce conflict between occupants.