
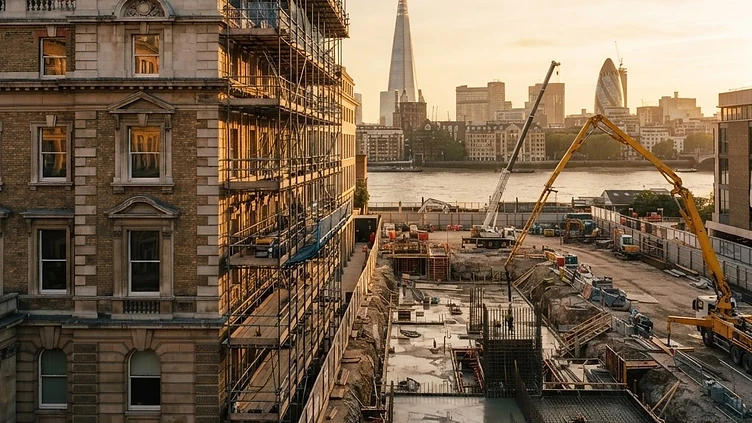
Navigating commercial property investment? Compare the funding structures of heavy refurbishment and ground-up development to find the right fit for your strategy.
Understanding the Landscape for Commercial Investors
For the serious investor, the decision between pursuing a heavy refurbishment project or starting a ground-up development represents two distinct risk-reward profiles. In the UK market, these paths require fundamentally different capital structures, planning strategies, and timelines. Understanding how to align your project with the correct funding mechanism is the difference between a high-yield asset and a capital-locked liability.
Heavy Refurbishment: Repurposing Existing Assets
Heavy refurbishment—often referred to as 'light industrial conversion' or 'comprehensive office-to-resi'—involves significant structural changes to an existing building. Unlike light cosmetic improvements, heavy refurbishment typically involves moving load-bearing walls, replacing mechanical and electrical systems, or extending the building footprint.
From a finance perspective, lenders view these projects through the lens of 'Asset Repositioning.' The primary risk is not ground stability or planning uncertainty, but rather 'hidden building conditions' uncovered during strip-out. Financing for this route often takes the form of a stretched senior loan or a structured bridge-to-term facility. These products are designed to cover the purchase price and the capital expenditure (CapEx) required to reach practical completion.
Ground-Up Development: Creating Value from the Dirt Up
Ground-up development is the process of building on vacant land or clearing a site to construct a new structure from scratch. This strategy offers total control over the design, energy efficiency (EPC rating), and final floorplate layout. However, it introduces significant planning risk, environmental remediation requirements, and the necessity of managing a complex supply chain.
Because there is no income-producing asset during the construction phase, financing a ground-up project is inherently more rigorous. You will need to engage with specialist development finance providers who understand the nuances of build-cost inflation and the critical path of construction milestones. Unlike refurbishment, which may allow for a faster exit or a refinance onto a term loan, ground-up projects typically require a structured facility that advances funds in stages, verified by a Monitoring Surveyor (MS) who acts as the lender's eyes on the ground.
Choosing the Right Facility
When deciding which path to take, your finance strategy must consider your exit plan. If you are refurbishing an existing building, your exit might be selling the individual units or refinancing onto a long-term commercial investment mortgage once the building is fully let. Because the asset is already in situ, the loan-to-gross-development-value (LTGDV) is often higher, and the interest rates may be slightly more competitive compared to ground-up projects.
Conversely, ground-up development is a 'cradle to grave' operation. The funding must account for the initial acquisition of the site, the professional fees (architects, structural engineers, planning consultants), and the build cost. Interest roll-up is standard here, meaning you do not pay interest monthly; instead, the interest is added to the loan balance, which is then repaid upon the sale or refinance of the completed asset. This protects your cash flow during the intensive build phase but increases the total debt stack significantly.
Risk Assessment: Why Structure Matters
The primary difference in risk lies in the 'known versus unknown.' In a refurbishment, you know the building envelope, but you might discover asbestos or rot that halts progress. In ground-up, you know the ground conditions and structural design, but you are at the mercy of planning authorities and raw material prices.
For investors focused on off-market opportunities, the choice often comes down to the quality of the deal. An existing building with high-ceiling heights or historic character might present a superior ROI through refurbishment than a generic new build. Your finance facility should be as bespoke as the property itself. Engaging with lenders early—before you secure the site—allows you to stress-test your margins against current market volatility.
Key takeaways
- Heavy refurbishment offers lower planning risk but higher operational risk due to hidden building defects.
- Ground-up development provides total control over asset quality but requires longer timelines and more complex, staged funding.
- Interest roll-up is standard for ground-up development to protect liquidity during the construction phase.
- Always align your finance facility with your exit strategy, whether that is a full exit sale or a refinance onto a commercial investment mortgage.